Fact-Checking Mcdonald's Arch Card Policies: Do They Expire, Lose Value, or Charge Fees?
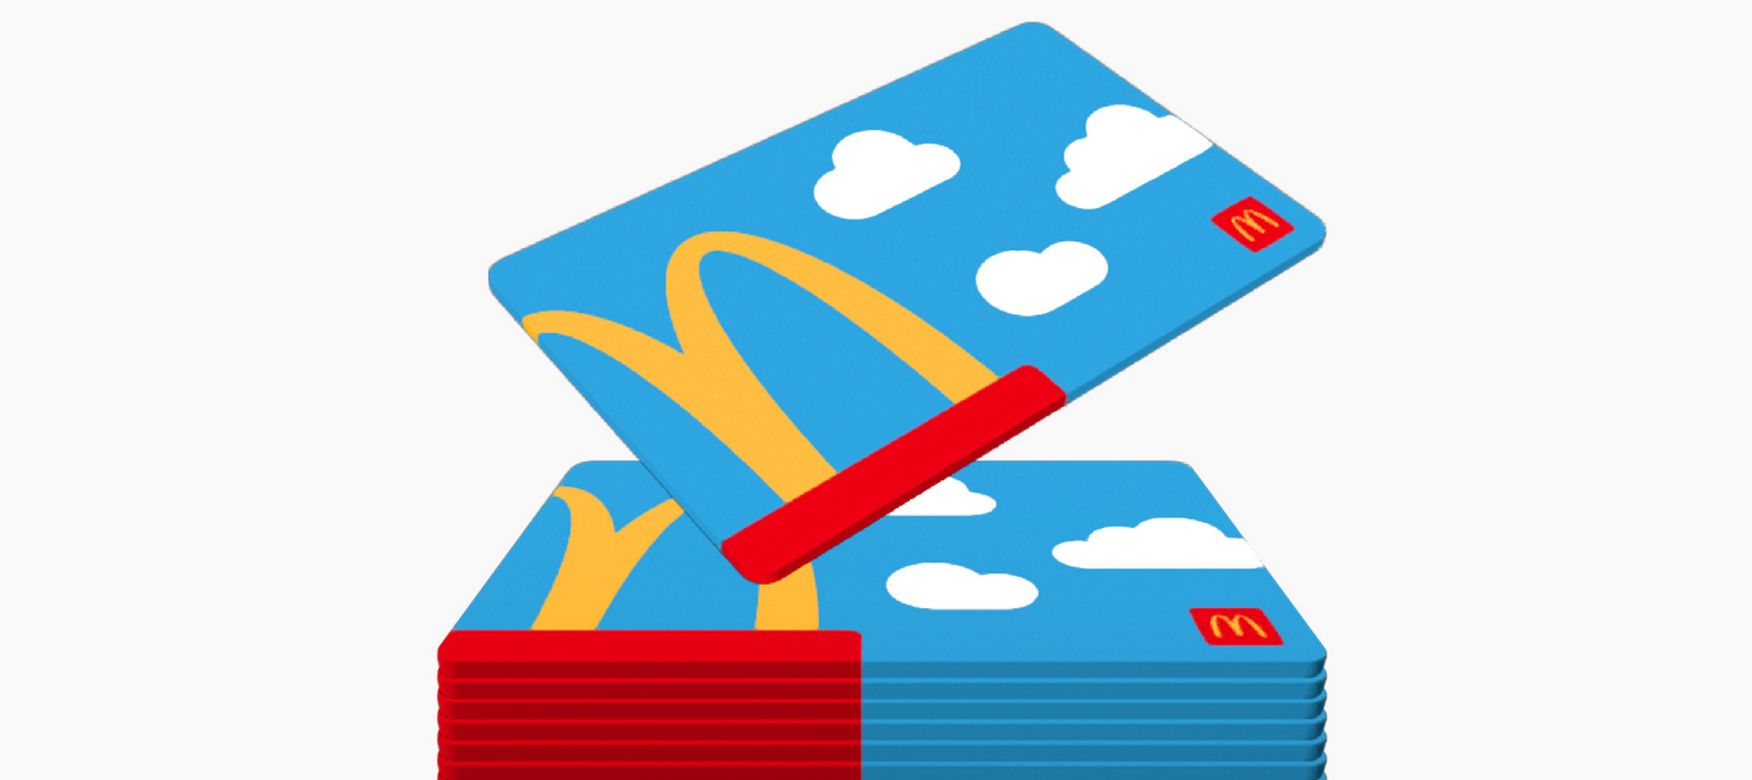
The primary source of consumer confusion involves how stored funds interact with modern smartphones. When McDonald's modernized its mobile application, customers expected that scanning an Arch Card barcode would instantly sweep the plastic balance into a central digital wallet. That is not how the backend operates.
Under current McDonald's mobile app integration protocols, adding an Arch Card creates an active payment token within the software. The plastic card remains active in the physical world. If a family member uses the physical plastic at a drive-thru, the app's displayed balance does not always update instantaneously. This lag leads to failed mobile pickup orders when the platform attempts to authorize nonexistent funds.
The interplay with loyalty programs creates further friction. An Arch Card is strictly a payment instrument, not a rewards account. Spending funds from an Arch Card earns loyalty points only when the customer independently scans their MyMcDonald's Rewards code before payment. Swiping a plastic card at the counter or handing it over as one of several drive-thru payment methods does not automatically award points. Thousands of consumers routinely forfeit reward points simply because they assumed the card itself tracked their dining history.